Gerardo Del Real,
Editor
Sept. 23, 2026
It’s Beaver Creek week… which means everyone has good news.
Global Lithium Resources (ASX: GL1) shares soared nearly 50% on Tuesday after the Australian developer agreed to an A$333 million (US$237 million) cash takeover by UAE-headquartered Titan Australia Mining Pty Ltd.
Artemis Gold has signed a definitive agreement to acquire Vista Gold in an all-share transaction valued at approximately US$427 million (C$598.9 million).
China Rare Earth Group is in talks to acquire Shenghe Resources.
Gold is sitting comfortably above the $4,000 level, which I believe is a new floor, currently at $4,340. Silver is holding the $66 level. Uranium is slowly but surely trickling higher, now above the $90/lb level.
Then there’s copper flirting with new all-time highs once again.
Get used to that.
Copper is increasingly being targeted as a critical metal by the kind of capital that doesn’t really care what it pays for. It cares that it can find enough.
Here’s 40-plus-year mining veteran Robert Friedland’s take on it… the same Robert Friedland who was at the White House earlier this year.
“We are constantly in discussion with sovereign wealth funds and major mining companies,” Friedland said in an interview. “And now most recently, Silicon Valley hyperscalers are very worried about where metal is going to come from. We’re seeing unconventional interest in mining that I never saw in my 45 years in mining.”
That’s a trend that will accelerate.
Despite a 50% pop over the past year, the real fireworks have yet to begin.
You want to build a house? Copper.
You want to rebuild your country? Copper.
You want to win the AI race? Copper.
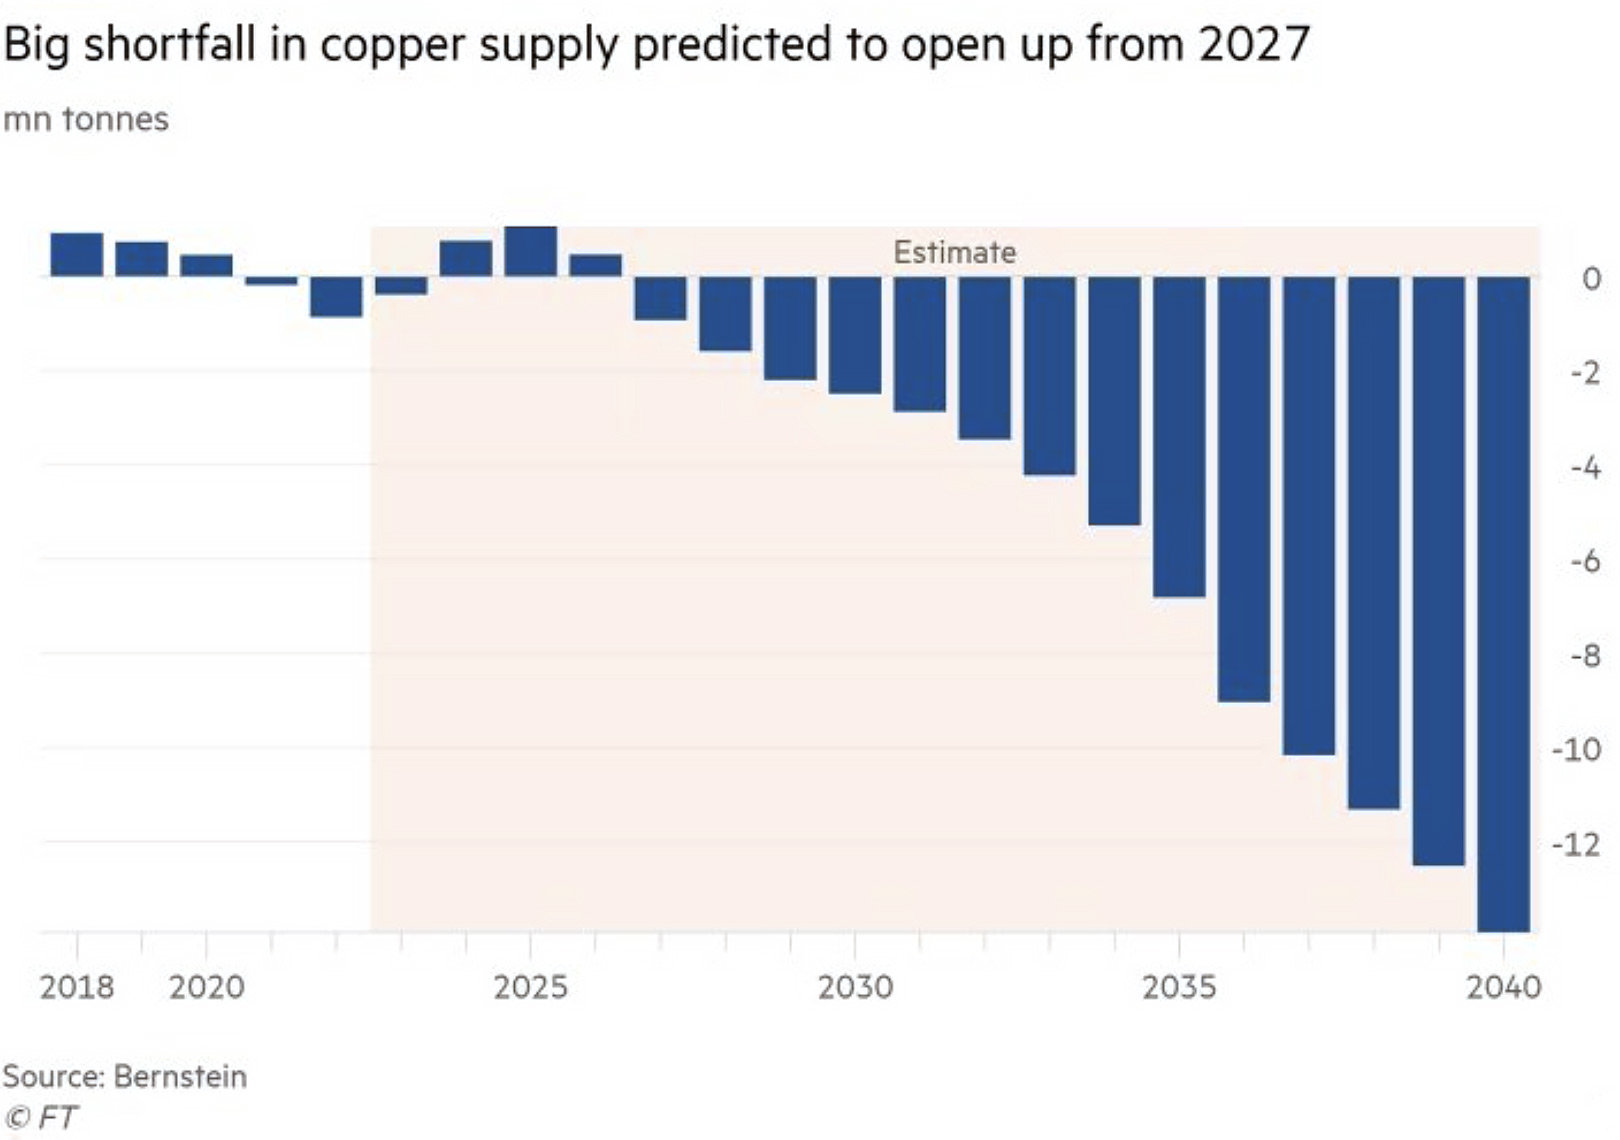
Prices are at record highs, and the real deficits haven’t kicked in yet. The record-setting price action is the precursor to that.
The structural deficits that are coming cannot be undone by higher prices. Soon, countries will not care what they pay for copper. They’ll just want to make sure they have enough for their needs.
The shortages are being met with production declines from the world’s biggest producers. Codelco and Freeport-McMoRan posted double-digit production declines.
Weather, lower grades, and strangled supply chains from tariffs are just some of the reasons for the surge in price.
The Kobeissi Letter reported that U.S. data center construction spending surged 57% YoY in July to a record annualized rate of $75 billion.
This follows a 46% YoY increase in June and marks the largest YoY increase since mid-2025.
Since the start of 2021, U.S. data center construction spending has soared by $66 billion, or 717%.
Since the end of 2023 alone, data center construction has risen by $51 billion.
Over the same period, all other private construction spending, including houses, shopping centers and offices, has declined by $120 billion.
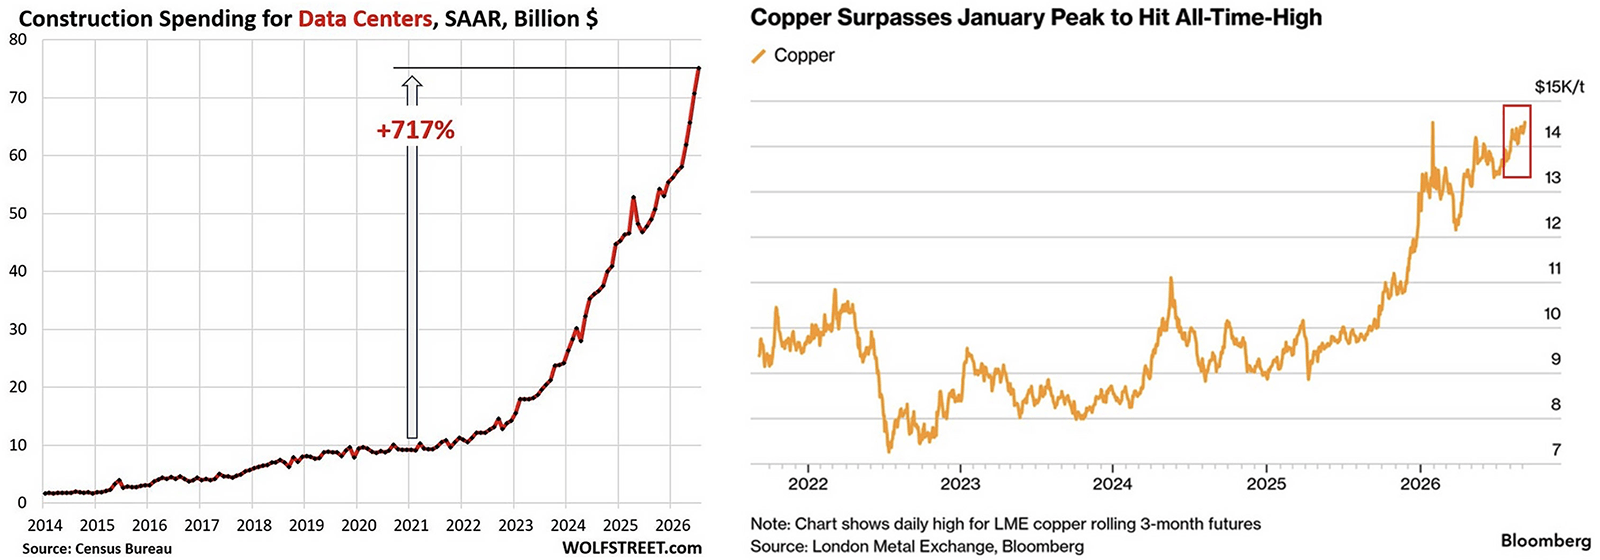
The copper bull market is in full gear with lots of runway ahead of it. There simply haven’t been enough discoveries of significance over the last decade to support the demand that exists.
There are not enough projects in the pipeline, and current projects are struggling to maintain current production profiles, let alone increased production.
That bodes well for us as the Junior Resource Monthly and Junior Resource Speculator portfolios are positioned well across the commodity space.
Let's get it,

Gerardo Del Real
Editor, Bizarro World